
Many dealerships have taken an important step toward lowering payment acceptance costs by implementing credit card surcharging. By using a surcharge to pass eligible credit card processing fees to customers who choose to pay with credit, they're protecting more revenue from every repair order, parts purchase, and vehicle sale.
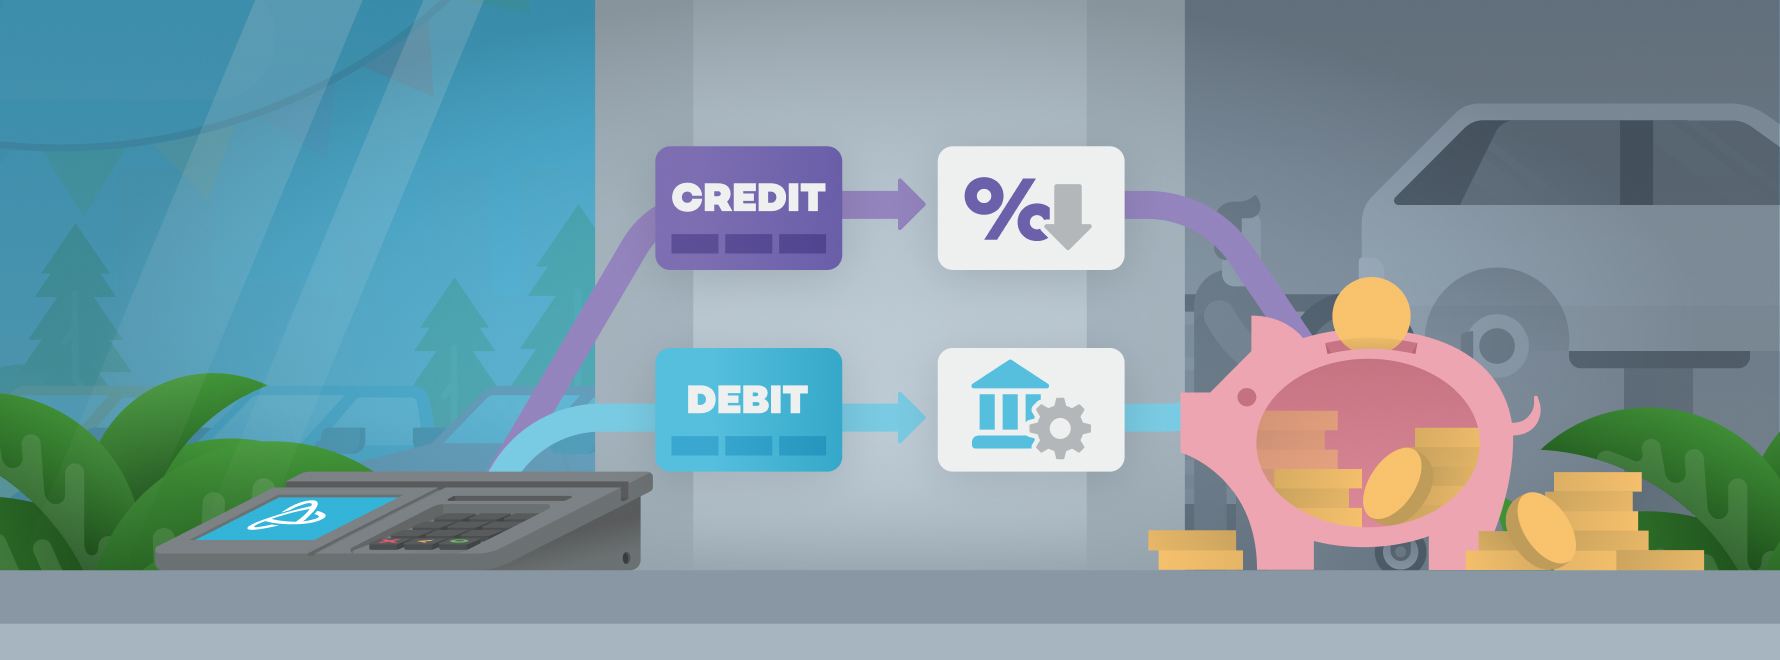
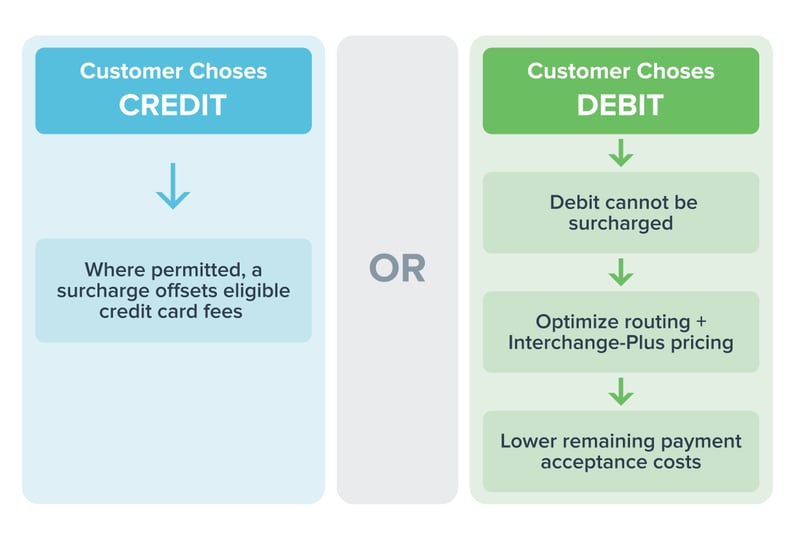
But there's one piece of the equation that's essential to understand: Debit cards cannot be surcharged.
In fact, once surcharging is in place, many customers may naturally choose to pay with debit instead of credit. That freedom of choice helps customers avoid a surcharge, but it can also mean that debit transactions become a larger share of your dealership’s payment volume mix.
While those transactions generally cost less to process than credit cards, not all debit transactions cost the same. And depending on how your payment processor handles them, your dealership could still be paying too much.
The good news? Modern payment technology can help reduce debit processing costs while maintaining a familiar checkout experience for your employees or customers.
What Is Debit Card Processing?
Every time a customer pays with a debit card, several organizations work together behind the scenes to move money securely from the customer's bank account into your dealership's account.
That transaction typically involves five key participants:
- Your dealership, which accepts the payment.
- Your payment processor, which securely transmits payment information and communicates with the financial institutions involved.
- The card brand or PIN debit network, which routes transaction information between the relevant parties .
- Your acquiring bank, which receives funds on your dealership's behalf.
- The customer's issuing bank, which verifies available funds and approves or declines the transaction.
Whether the customer is paying for an oil change, a new set of tires, or the purchase of a vehicle, authorization typically happens in just a few seconds, while settlement and funding occur later.
Debit transactions generally fall into two categories:
- Card-present, where the customer taps, inserts or swipes their card at the dealership.
- Card-not-present, such as online parts purchases or service deposits and balances made through your website.
Because card-present transactions typically carry lower fraud risk, they often have lower processing costs.
How Debit Card Processing Works
Although customers only see a quick approval message, several steps are actually taking place behind the scenes.
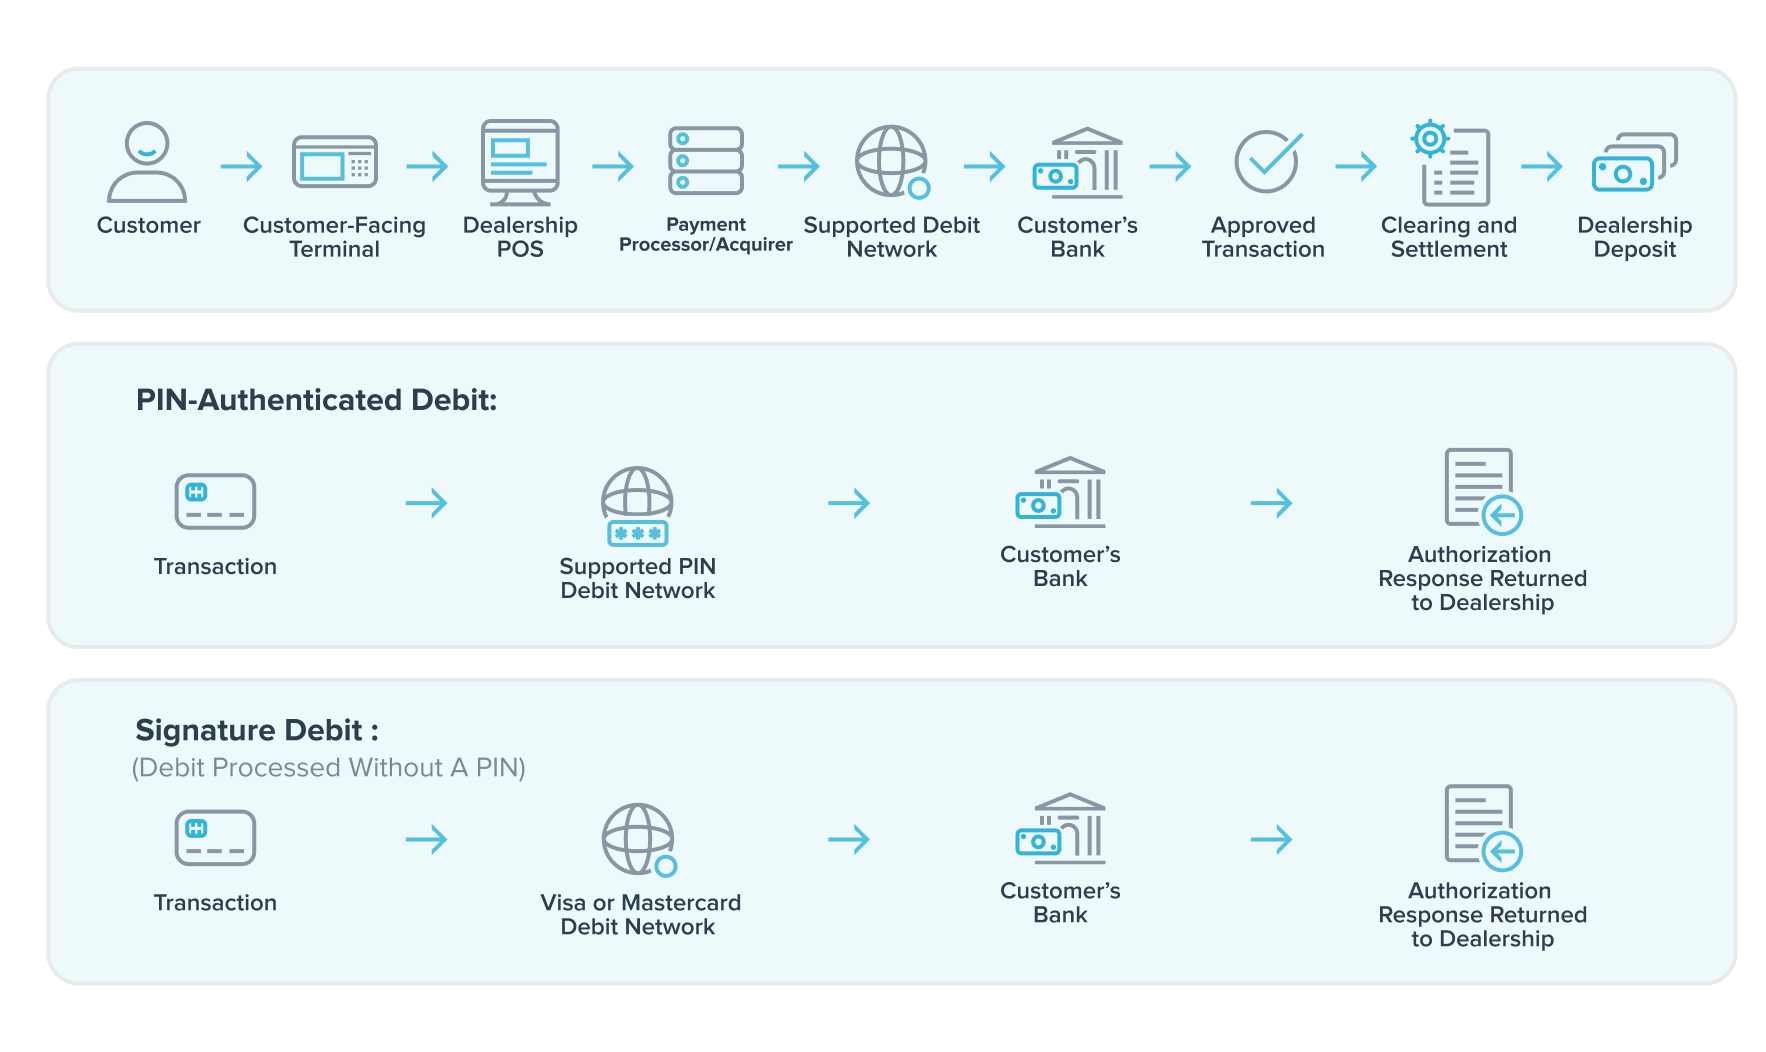
- The customer taps, inserts, or swipes their debit card.
- Your dealership's payment system securely sends the transaction to your payment processor.
- The processor routes the transaction through a supported debit network.
- The customer's bank approves or declines the purchase.
- If approved, the transaction is subsequently settled, and funds are deposited into your dealership’s account.
Most debit transactions follow a similar process. Where costs begin to differ is in how the transaction is routed.
Signature Debit vs. PIN Debit: Why the Difference Matters
Many merchants assume all debit card transactions cost about the same. They don't.
Although both signature debit and PIN debit typically access funds from a customer's checking account, they don't always follow the same path through the payments system. That difference can affect your dealership's processing costs.
Signature Debit
Signature debit transactions are typically authorized without the customer entering a PIN. Depending on the card and payment terminal, customers may tap, insert, or swipe their card and complete the purchase without entering a PIN.
These transactions are commonly routed through major card networks like Visa and Mastercard and often carry higher wholesale processing costs than comparable PIN debit transactions.
PIN Debit
By contrast, PIN debit transactions require customers to enter their personal identification number (PIN) to authenticate the purchase.
Because the PIN provides another layer of verification, these transactions generally present lower fraud risk. PIN debit transactions may be routed through one of several debit networks enabled for the card. which often carry lower wholesale interchange costs.
Why Both Types Exist
Neither payment method is "better."
While signature debit offers the speed and convenience customers expect for many everyday purchases, including contactless payments and some digital payment experiences, PIN debit provides additional authentication and is commonly used for many in-person transactions.
How a debit transaction is authenticated and routed depends on several factors, including the payment environment, the customer's authentication method, the networks enabled for the card, the capabilities of the payment terminal, and the processor’s routing configuration.
Why Your Payment Processor Matters
This is where many dealerships may unknowingly leave money on the table.
Customers can only choose PIN debit when they have access to a terminal to enter their PIN. Yet some processors provide terminals that sit behind the counter, making PIN entry inconvenient or unavailable.
A modern, customer-facing terminal puts the choice where it belongs: in the customer’s hands. Customers can clearly see the transaction details and enter their PIN privately when they choose debit.
This creates a smoother checkout experience while helping dealerships process more eligible transactions as PIN debit. Combined with transparent pricing, the right terminal setup can improve the customer experience and may help dealerships lower debit processing costs.
Why Some Dealerships Pay More for Debit Processing
It’s important to note that not every payment processor handles pricing the same way.
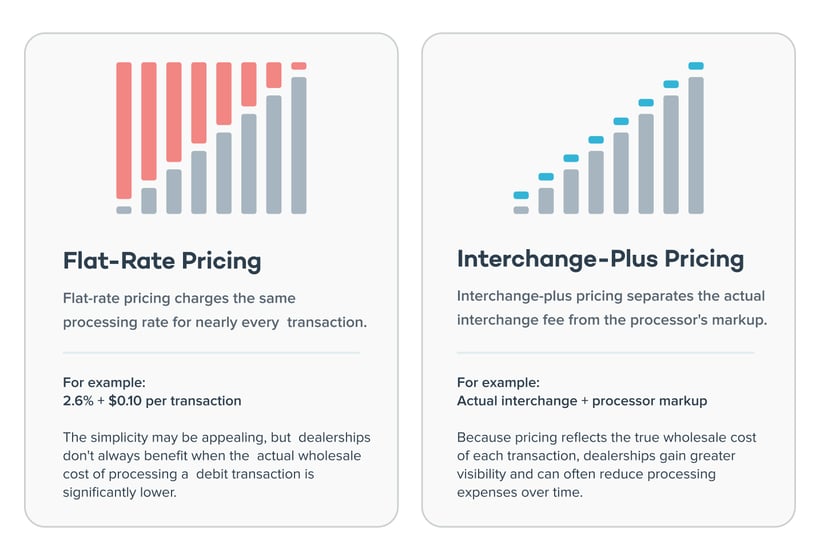
Some providers bundle debit transactions into flat-rate pricing that averages costs together. While that may simplify billing, it can also make it difficult for dealerships to benefit from the lower wholesale costs associated with many PIN debit transactions.
Other processors use transparent interchange-plus pricing, separating wholesale interchange costs from the processor's markup.
That visibility in the pricing structure can help dealerships better understand what they're paying and ensure lower-cost transactions remain lower cost.
Flat-Rate vs. Interchange-Plus Pricing
The pricing model behind your payment processing can have a meaningful impact on your total payment acceptance costs.
Debit Card Fees vs. Credit Card Fees
Credit and debit cards may look similar to customers, but they can have different payment processing costs.
|
Debit Cards |
Credit Cards |
|
Generally lower interchange costs |
Generally higher interchange costs |
|
Cannot be surcharged |
Eligible transactions may be surcharged where permitted |
|
Savings may come through optimized routing and transparent pricing |
Savings may come through surcharging and pricing optimization |
Many dealerships focus on reducing credit card processing costs through compliant surcharging where permitted, and for good reason.
But because debit cards cannot be surcharged under card network rules, optimizing debit processing may present another opportunity to lower payment acceptance costs.
The strongest strategy isn’t choosing one or the other. It’s using both.
How Dealerships Can Reduce Debit Processing Costs
If you're looking to lower payment acceptance costs, start by evaluating how debit transactions are handled today.
Look for opportunities to:
- Review your merchant statements for hidden fees or bundled pricing.
- Choose a processor that offers a simple flat rate for credit transactions and interchange-plus pricing on debit.
- Ensure eligible debit transactions are routed cost-effectively.
- Use integrated payment technology that can help improve operational efficiency and reduce manual reconciliation.
- Periodically review payment performance as transaction volumes and customer behavior evolve.
Small savings on debit transactions can add up quickly across thousands of repair orders and vehicle sales each year.
Questions to Ask Your Payment Processor
Before renewing your processing agreement, ask:
- Do you offer interchange-plus pricing?
- How transparent are your processing fees?
- Do you support optimized debit routing?
- Can you review my current merchant statement for savings opportunities?
- How well does your payment platform work with my DMS and dealership workflows?
- Can you help reduce both credit and debit payment acceptance costs?
The answers can reveal whether your processor is simply processing payments or actively helping your dealership improve profitability.
The Bottom Line
Credit card surcharging can be an effective way to offset eligible credit card processing costs.
But it isn't the entire story.
As more customers choose debit cards, optimizing debit processing becomes one of the most effective ways dealerships may be able to continue reducing payment acceptance expenses.
The right payment processor combines transparent interchange-plus pricing with intelligent debit routing capabilities, helping ensure your dealership pays less in processing costs while maintaining a fast, seamless checkout experience for every customer.